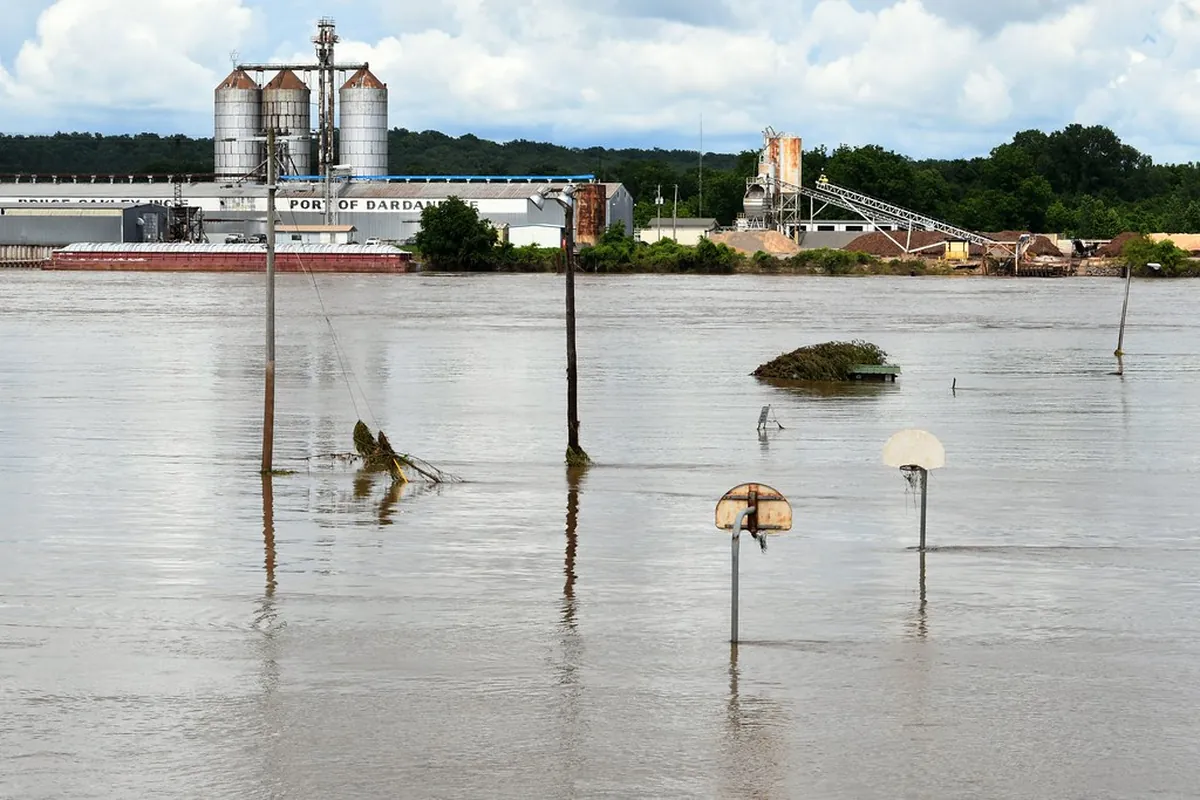
Tropical systems far from the sea
On August 28, 2011, Tropical Storm Irene stalled over Vermont and dropped heavy rain on already wet ground. Rivers rose in hours. Hundreds of roads and many bridges were damaged or destroyed, towns such as Wilmington, Rochester, Bethel and Killington were cut off, and the state office complex in Waterbury flooded. In July 2024 the remnants of Hurricane Beryl brought another round of flash flooding, the second severe July flood in two years.
Tropical storm claim appraisal in Vermont is about separating what each policy pays for and valuing the covered part fully.
Wind and rain versus flood
Standard homeowners and commercial policies generally exclude flood, which is usually covered only under a separate flood policy such as the National Flood Insurance Program. But a tropical system also brings wind, falling trees and rain that enters through openings the wind creates. Those are typically covered under the property policy.
- Roof and siding damage from wind, and interior damage from rain that came through it.
- Trees falling onto covered structures.
- Water that backed up through drains or sewers, if the policy carries that endorsement.
When both kinds of damage occur, the carriers can disagree over which caused what. Clear documentation of the water line, the roof openings and the timeline helps keep covered wind damage from being folded into an excluded flood.
Flood policies have appraisal too
The standard NFIP flood policy contains its own appraisal provision for disagreements over the value of covered property. Its deadlines and proof-of-loss rules are strict and different from a homeowners policy. If your claim involves a flood policy, read its conditions closely or speak with a professional before deadlines pass.
Questions about this service
Does my homeowners policy cover tropical storm damage?
Usually it covers wind and wind-driven rain through openings, subject to deductibles. Flood from rising water is generally excluded and needs separate flood coverage.
Can one loss involve two claims?
Yes. Many Irene-era losses involved both a homeowners claim and a flood claim on the same building.
Do you appraise NFIP claims?
We can value flood damage, but NFIP rules are strict. Read the policy’s appraisal and proof-of-loss provisions and act within its deadlines.