Why Vermont homes are hard to price
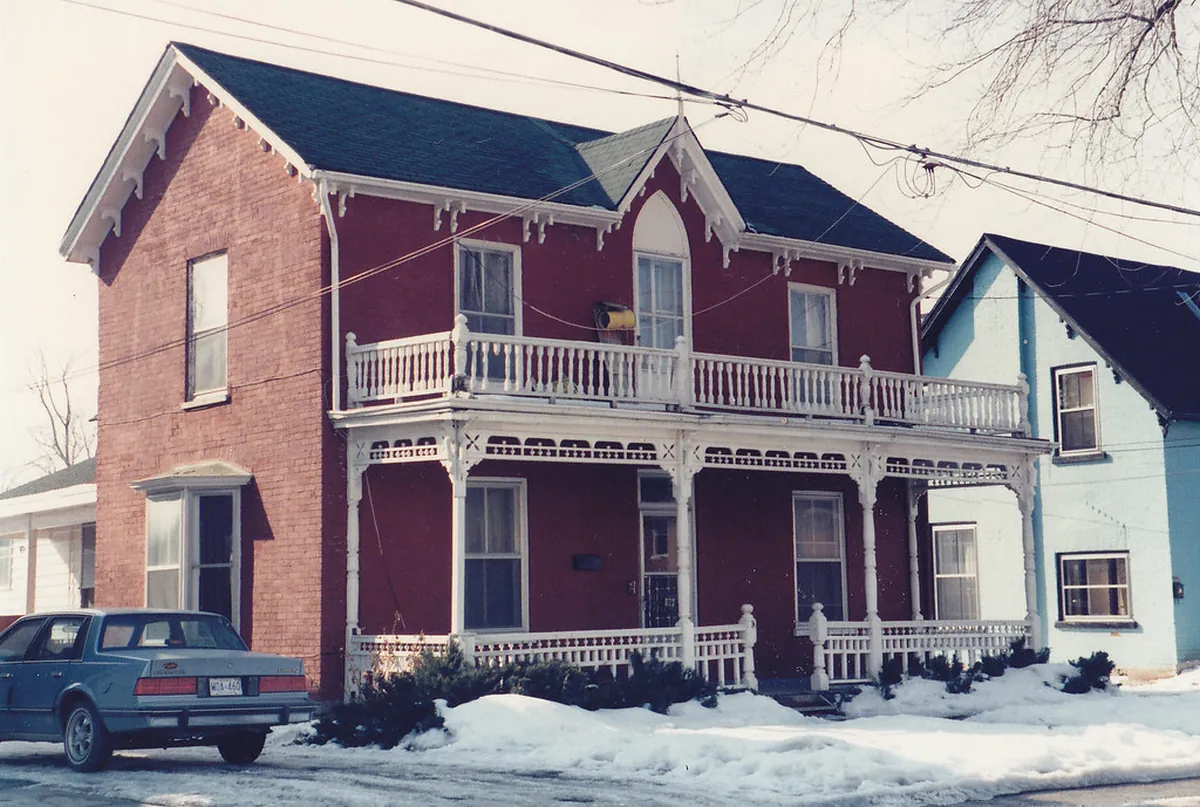
Vermont’s housing stock is old. A large share of homes predate 1940, and many have been added onto more than once: a timber-frame core, an ell, a connected barn, a 1970s shed dormer. That history matters in a claim. Plaster walls, wide-plank floors, slate roofs, rubble foundations and knob-and-tube wiring do not fit neatly into a software default, and a carrier’s estimate that assumes drywall and builder-grade trim can miss a large share of the real cost.
Homeowner claim appraisal in Vermont starts with understanding what was there before the loss, then pricing what it takes to restore it with like kind and quality.
Common gaps we find on residential estimates
- Matching. Partial replacement of siding, flooring or roofing that will not match what remains.
- Plaster and lath. Priced as drywall, or omitted from the demolition and haul-off.
- Code upgrades. Electrical, ice-and-water underlayment and other items required once work begins, if the policy includes ordinance or law coverage.
- Access and seasonality. Steep roofs, long driveways, winter protection and heat for interior drying.
- Contents and additional living expense. Often handled separately, but a dispute in the dwelling estimate can ripple into both.
Seasonal homes and camps
Second homes in the Mad River Valley, around Stowe or on Lake Champlain and the Northeast Kingdom lakes bring their own issues: vacancy and unoccupancy wording, heat-maintenance conditions for freeze losses, and seasonal road access that delays inspections. We read those conditions before we value anything, because they shape what the carrier will pay even after the amount is set.
Condos and townhouses
For unit owners, the master policy and your HO-6 policy split the loss. We help sort which estimate covers which part, so the right numbers go to the right appraisal.
How the work starts
Send the carrier’s estimate, your declarations page and any photos. We review them, tell you where we see differences and whether appraisal makes sense, and only then talk about engagement.
Questions about this service
Do you handle mobile and manufactured homes?
Yes. The scope and pricing differ, but the appraisal process is the same.
My house is very old. Does that hurt my claim?
Not by itself. Age affects depreciation on an actual-cash-value basis, but replacement cost policies are meant to pay to repair with like kind and quality.
Can you help after I already accepted a payment?
Often, if the claim is still open and policy deadlines have not run. Accepting an undisputed payment does not usually end the claim, but check any release you signed.