Appraisal Clause Representation
We serve as your named appraiser once the appraisal clause is invoked, from inspection through signed award.
Twelve services, one job: an accurate, defensible value for your loss. Start with an estimate review, bring us in once appraisal is demanded, or ask us to serve as a neutral umpire.
We serve as your named appraiser once the appraisal clause is invoked, from inspection through signed award.
Independent valuation for houses, camps and condos when the carrier’s estimate falls short of the real repair.
Appraisal for inns, shops, farms, churches, multifamily buildings and condo associations with disputed property losses.
Measured roof scopes for hail, wind and snow damage: slopes, pitch, underlayment, flashing and matching.
Valuation for straight-line wind, microburst and rare tornado losses, from lifted shingles to structural repair.
Help after the remnants of tropical systems bring wind and rain inland, as Irene and Beryl did.
Burst pipes, failed fittings, sudden leaks and wind-driven rain: scopes that include drying, demolition and rebuild.
Structure fires, chimney fires and smoke losses, including soot cleaning, odor control and contents.
Vermont’s signature winter claims: meltwater backing up under shingles and pipes that split in a cold snap.
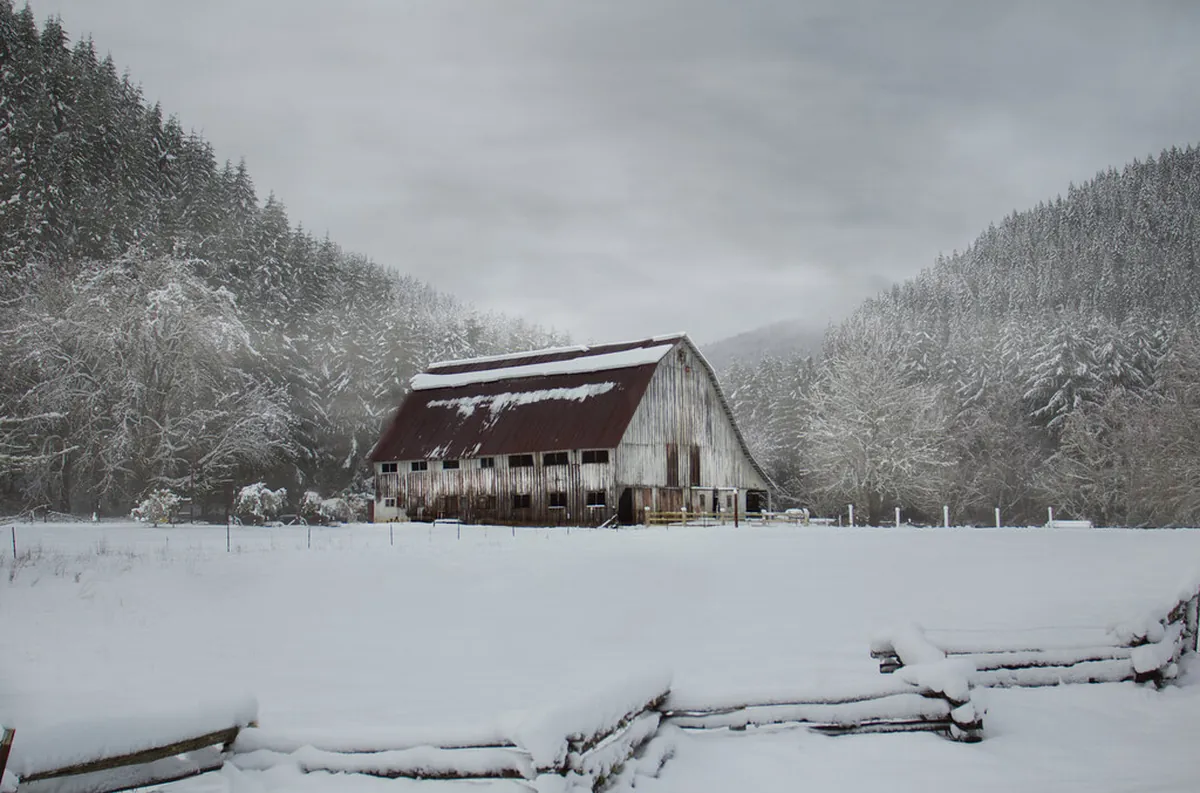
Roof and structural collapse from heavy snow and ice, from sagging rafters to failed barn roofs.
A line-by-line read of the carrier’s estimate against your property, before you decide on appraisal.
Neutral umpire service for appraisal panels that cannot agree on the amount of loss.
Before anyone demands appraisal, it helps to know exactly where the carrier’s estimate falls short and what the gap is worth. A review answers that in days, and many disputes close right there.
About estimate reviewsYes. Many clients start with an estimate review and decide later whether to demand appraisal.
Yes: inns, shops, multifamily buildings, condo associations, churches, barns and other farm structures.
We value covered damage. Flood from rising water is usually a separate policy with its own rules; we will explain how that affects your claim.
Send us the estimate. We will read it line by line and tell you what we see.