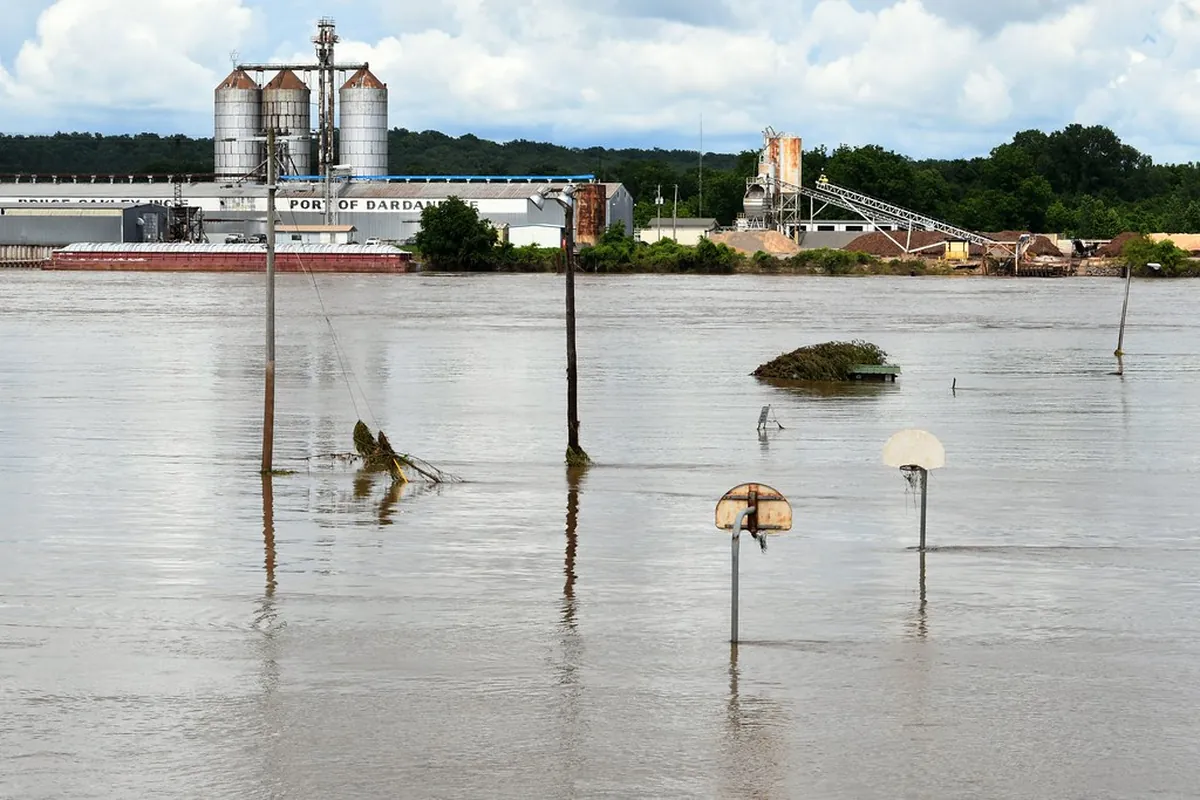
Vermont learned hard lessons about water in 2011, 2023 and 2024. After Tropical Storm Irene, and again after the July floods of 2023 and the remnants of Hurricane Beryl in 2024, thousands of owners discovered that the word “water” covers several very different kinds of insurance claims.
Four kinds of water
- Rain through a storm opening. Wind tears off shingles or a tree punctures the roof, and rain pours in. Usually covered by a homeowners or commercial policy.
- Plumbing and appliance water. A burst pipe or failed fitting. Usually covered as sudden and accidental discharge.
- Sewer or drain backup. Water pushed up through floor drains or toilets. Often covered only by an endorsement, with a separate limit.
- Flood. Rising surface water from a river, brook or overland flow. Generally excluded from homeowners policies and covered by a separate flood policy.
Why the distinction matters
When a storm brings wind and floodwater together, carriers may argue over which caused what. A wall that was wet from both rising water and a roof leak can end up in a gap between two policies. Clear evidence of the high-water mark, the roof openings and the timing protects the covered part of the claim.
What to document
- Photograph and measure the high-water line inside and outside.
- Photograph roof, siding and window damage separately, from outside and inside.
- Note which rooms were wet from above and which from below.
- Keep receipts for pumping, extraction and drying for each area.
Flood policies run on their own clock
National Flood Insurance Program policies have strict proof-of-loss deadlines, usually measured from the date of loss, and their own appraisal provision for disputes over the value of covered damage. They also limit coverage in basements. Read the flood policy separately from your homeowners policy.
Where appraisal fits
If the carrier accepts the wind or plumbing damage but undervalues it, appraisal can address the amount. If the dispute is whether the water was flood or covered water, that is a coverage question. Our tropical storm claim appraisal page explains how we handle mixed losses.
This guide is general information, not legal advice. Your policy’s wording controls.